
Author
Eliana RodriguezPublished
Aug th, 2026Category
BlogRetirement income does not have to come solely from withdrawals or market performance. A well-structured business can add recurring cash flow, an asset with resale potential, and greater control over how your wealth is built before and during retirement.
Schedule a consultation to explore salon suite franchise ownership.
A retirement planning franchise can support long-term wealth building through recurring suite rental income. It adds a semi-absentee operating model and a business with resale potential. Salons by JC operates across 160+ locations, giving qualified investors an established franchise platform to evaluate alongside other retirement assets.
This approach still requires significant capital, careful due diligence, and a realistic operating plan. The key question is how the model can produce income while allowing an owner to limit day-to-day involvement. Understanding that question starts with the revenue created by suite leases and related services.
How a Retirement Planning Franchise Generates Income in Retirement
A retirement planning franchise generates income through recurring weekly suite rentals, convenience fees, and the resale value of the operating business. A trained manager handles daily operations, which suits a semi-absentee retirement lifestyle.
A salon suite franchise can create retirement income through an operating business tied to recurring occupancy, rather than relying on a single product or one-time transaction. The model combines weekly suite leases with convenience fees, giving the location more than one potential revenue stream. Results depend on market conditions, execution, occupancy, expenses, and financing, so investors should evaluate the opportunity through detailed financial projections rather than assume a fixed return.
Rental income from suite leases
Salons by JC leases private suites to independent beauty and wellness professionals. Rent is collected weekly, which can create a regular cash-flow cadence and make revenue easier to monitor than a business dependent on sporadic large sales. Convenience fees provide an additional revenue source connected to the suite-rental experience.
Occupancy and retention remain central to the economics. Salons by JC reports a 92% lease renewal rate, a performance measure that can help reduce vacancy risk when supported by strong local demand and effective operations. Renewals do not eliminate turnover or guarantee future revenue, but they can support more predictable planning than a model that must constantly replace customers.
For owners approaching retirement, this structure may complement other income sources while the business continues operating under professional management. The semi-absentee franchise model explains how ownership can be structured around oversight instead of performing the daily service work.
Social Security treatment also requires careful planning. The Social Security Administration states that income derived solely from owning an income-producing business may be excluded from the earnings test. That exclusion applies when no income is attributable to the beneficiary’s services after entitlement. The rule is fact-specific, and owners should review the details with the SSA and a qualified tax professional before relying on it. See the SSA policy guidance on self-employment earnings.
A business you can sell later
Retirement income is not limited to monthly or weekly distributions. A profitable, well-documented franchise location may also become a business asset with resale value. A buyer may evaluate its lease portfolio, renewal history, operating performance, management systems, location, and future growth potential. That creates a possible second wealth event when an owner is ready to exit.
Appreciation is not automatic. It depends on sustainable cash flow, the condition of the property and suites, market demand, contract quality, financial records, and the terms of a potential sale. Owners who build reliable operations and maintain accurate reporting can make the business easier for a buyer to understand and evaluate. This combination of ongoing operating income and potential resale value is why a salon suite franchise may fit into a broader retirement strategy.
Salon Suite Franchises vs. 401(k)s and Rental Real Estate
Compared with a 401(k) or rental real estate, a salon suite franchise offers a controlled operating asset with recurring suite-rental income. Tax-planning opportunities, and a business that may be sold later. It requires substantial capital and disciplined oversight.
Retirement income planning works best when each asset has a clear job. A 401(k) can provide diversified, tax-advantaged savings, while rental real estate may provide property-backed income and appreciation. A salon suite franchise adds an operating business to that mix, with potential income from recurring suite leases and a business asset that may be sold later. Each option has different requirements, risks, and levels of control.
The comparison below is a starting point, not a promise of performance. A franchise is an investment-grade business that requires substantial capital and active oversight of strategic decisions, even when a manager handles daily operations.
| Factor | 401(k) | Rental real estate | Salon suite franchise |
|---|---|---|---|
| Income control | Withdrawals depend on account balance, market performance, and distribution strategy. | Owner controls rents, leases, and property operations, subject to demand and vacancy. | Owner controls strategic decisions and leasing standards, with recurring suite rentals supporting revenue. |
| Growth potential | Growth is tied primarily to contributions and investment performance. | Potential growth comes from rent, property value, and improvements. | Potential growth can come from suite occupancy, operating performance, expansion, and eventual resale. Results are not guaranteed. |
| Tax treatment | Contributions and withdrawals follow plan rules and individual tax circumstances. | Rental income and expenses are reported under applicable property and business tax rules. | Business income, expenses, and deductions depend on entity structure and individual circumstances. Professional tax advice is essential. |
| Hands-on time | Generally low after contributions and investments are set up. | Ranges from limited oversight to substantial work with tenants, repairs, and vendors. | A Concierge Manager supports daily operations, but ownership still requires financial and strategic oversight. |
| Resale and legacy value | Account assets can transfer according to beneficiary and estate planning rules. | Property can be sold, refinanced, or transferred as part of an estate. | The operating business may be sold or transferred, subject to buyer demand, franchise terms, and performance. |
Capital requirements are a decisive distinction. Salons by JC lists a total initial investment of approximately $1.3 million to $2.0 million, with a minimum of $500,000 in liquid capital and $750,000 preferred. That threshold places the model in a different category from making a routine 401(k) contribution. It also means prospective owners should evaluate liquidity, financing, reserves, and downside scenarios before proceeding.
Rental real estate and salon suite franchising share an underlying real-estate component, but the operating model differs. A salon suite location leases space to independent beauty and wellness professionals, creating a business environment rather than a single residential tenancy. Review the guide to franchise vs. rental property for a deeper comparison, then use this how to invest money resource to consider how the asset could fit within a broader retirement plan.
Request investment details to compare a franchise against your current retirement portfolio.
Tax Advantages That Make Franchise Income Retirement-Friendly
Franchise income can become retirement-friendly through the 20% qualified business income deduction, depreciation on qualifying assets, and ordinary business deductions. Benefits depend on entity structure, ownership role, and current tax law.
Tax treatment can affect how much franchise income remains available for reinvestment, distributions, or retirement spending. A franchise may offer several planning opportunities, but the benefit depends on the entity structure, the owner’s role, the property’s financing, and current tax law. These are planning considerations, not individualized tax advice.
The 20% QBI deduction
Many franchise owners operate through a pass-through entity, such as an S corporation, partnership, or sole proprietorship. Under Section 199A, eligible pass-through business owners may deduct up to 20% of qualified business income. The deduction is subject to eligibility rules, taxable-income thresholds, wage and property limitations, and other restrictions. The IRS explains the qualified business income deduction in its guidance on Section 199A.
The phrase “up to” matters. A 20% deduction is not automatic, and it does not mean an owner receives 20% of revenue tax-free. Qualified business income generally refers to business profit, not gross receipts. Salary paid to an owner may also be treated differently from pass-through profit. A tax professional can model the result using the owner’s actual income, entity type, payroll, and ownership structure.
Because retirement planning often spans multiple accounts and income sources, franchise owners should evaluate the deduction alongside retirement contributions, estimated taxes, and potential Social Security income. Reviewing salon suite franchise taxes can help prospective owners identify questions to raise before choosing an entity or signing a franchise agreement.
Depreciation and deductible business costs
Depreciation may help shield part of a franchise’s taxable profit when the business owns or improves qualifying assets. Depending on the structure, this can include build-out components, furniture, equipment, and other depreciable property. Depreciation is a tax deduction that spreads an asset’s cost over its useful life. It is not the same as a cash expense in the year claimed, and special rules may apply to improvements, real estate, and accelerated deductions.
Franchise operations may also have ordinary and necessary business expenses, including:
- Approved operating supplies and equipment
- Insurance and professional services
- Marketing and software
- Rent and interest, when properly connected to the business and documented.
Personal spending cannot simply be relabeled as a business deduction. Franchise fees and startup costs can receive different treatment from recurring operating expenses.
These deductions can improve after-tax cash flow, but they should not drive the investment decision by themselves. Prospective owners should review expected revenue, occupancy, debt service, payroll, and cash reserves with qualified advisors. The salon franchise financing guide can support that broader discussion, while a CPA or tax attorney can explain the rules that apply to the specific investment.
Why the Concierge Manager Model Fits a Retirement Lifestyle
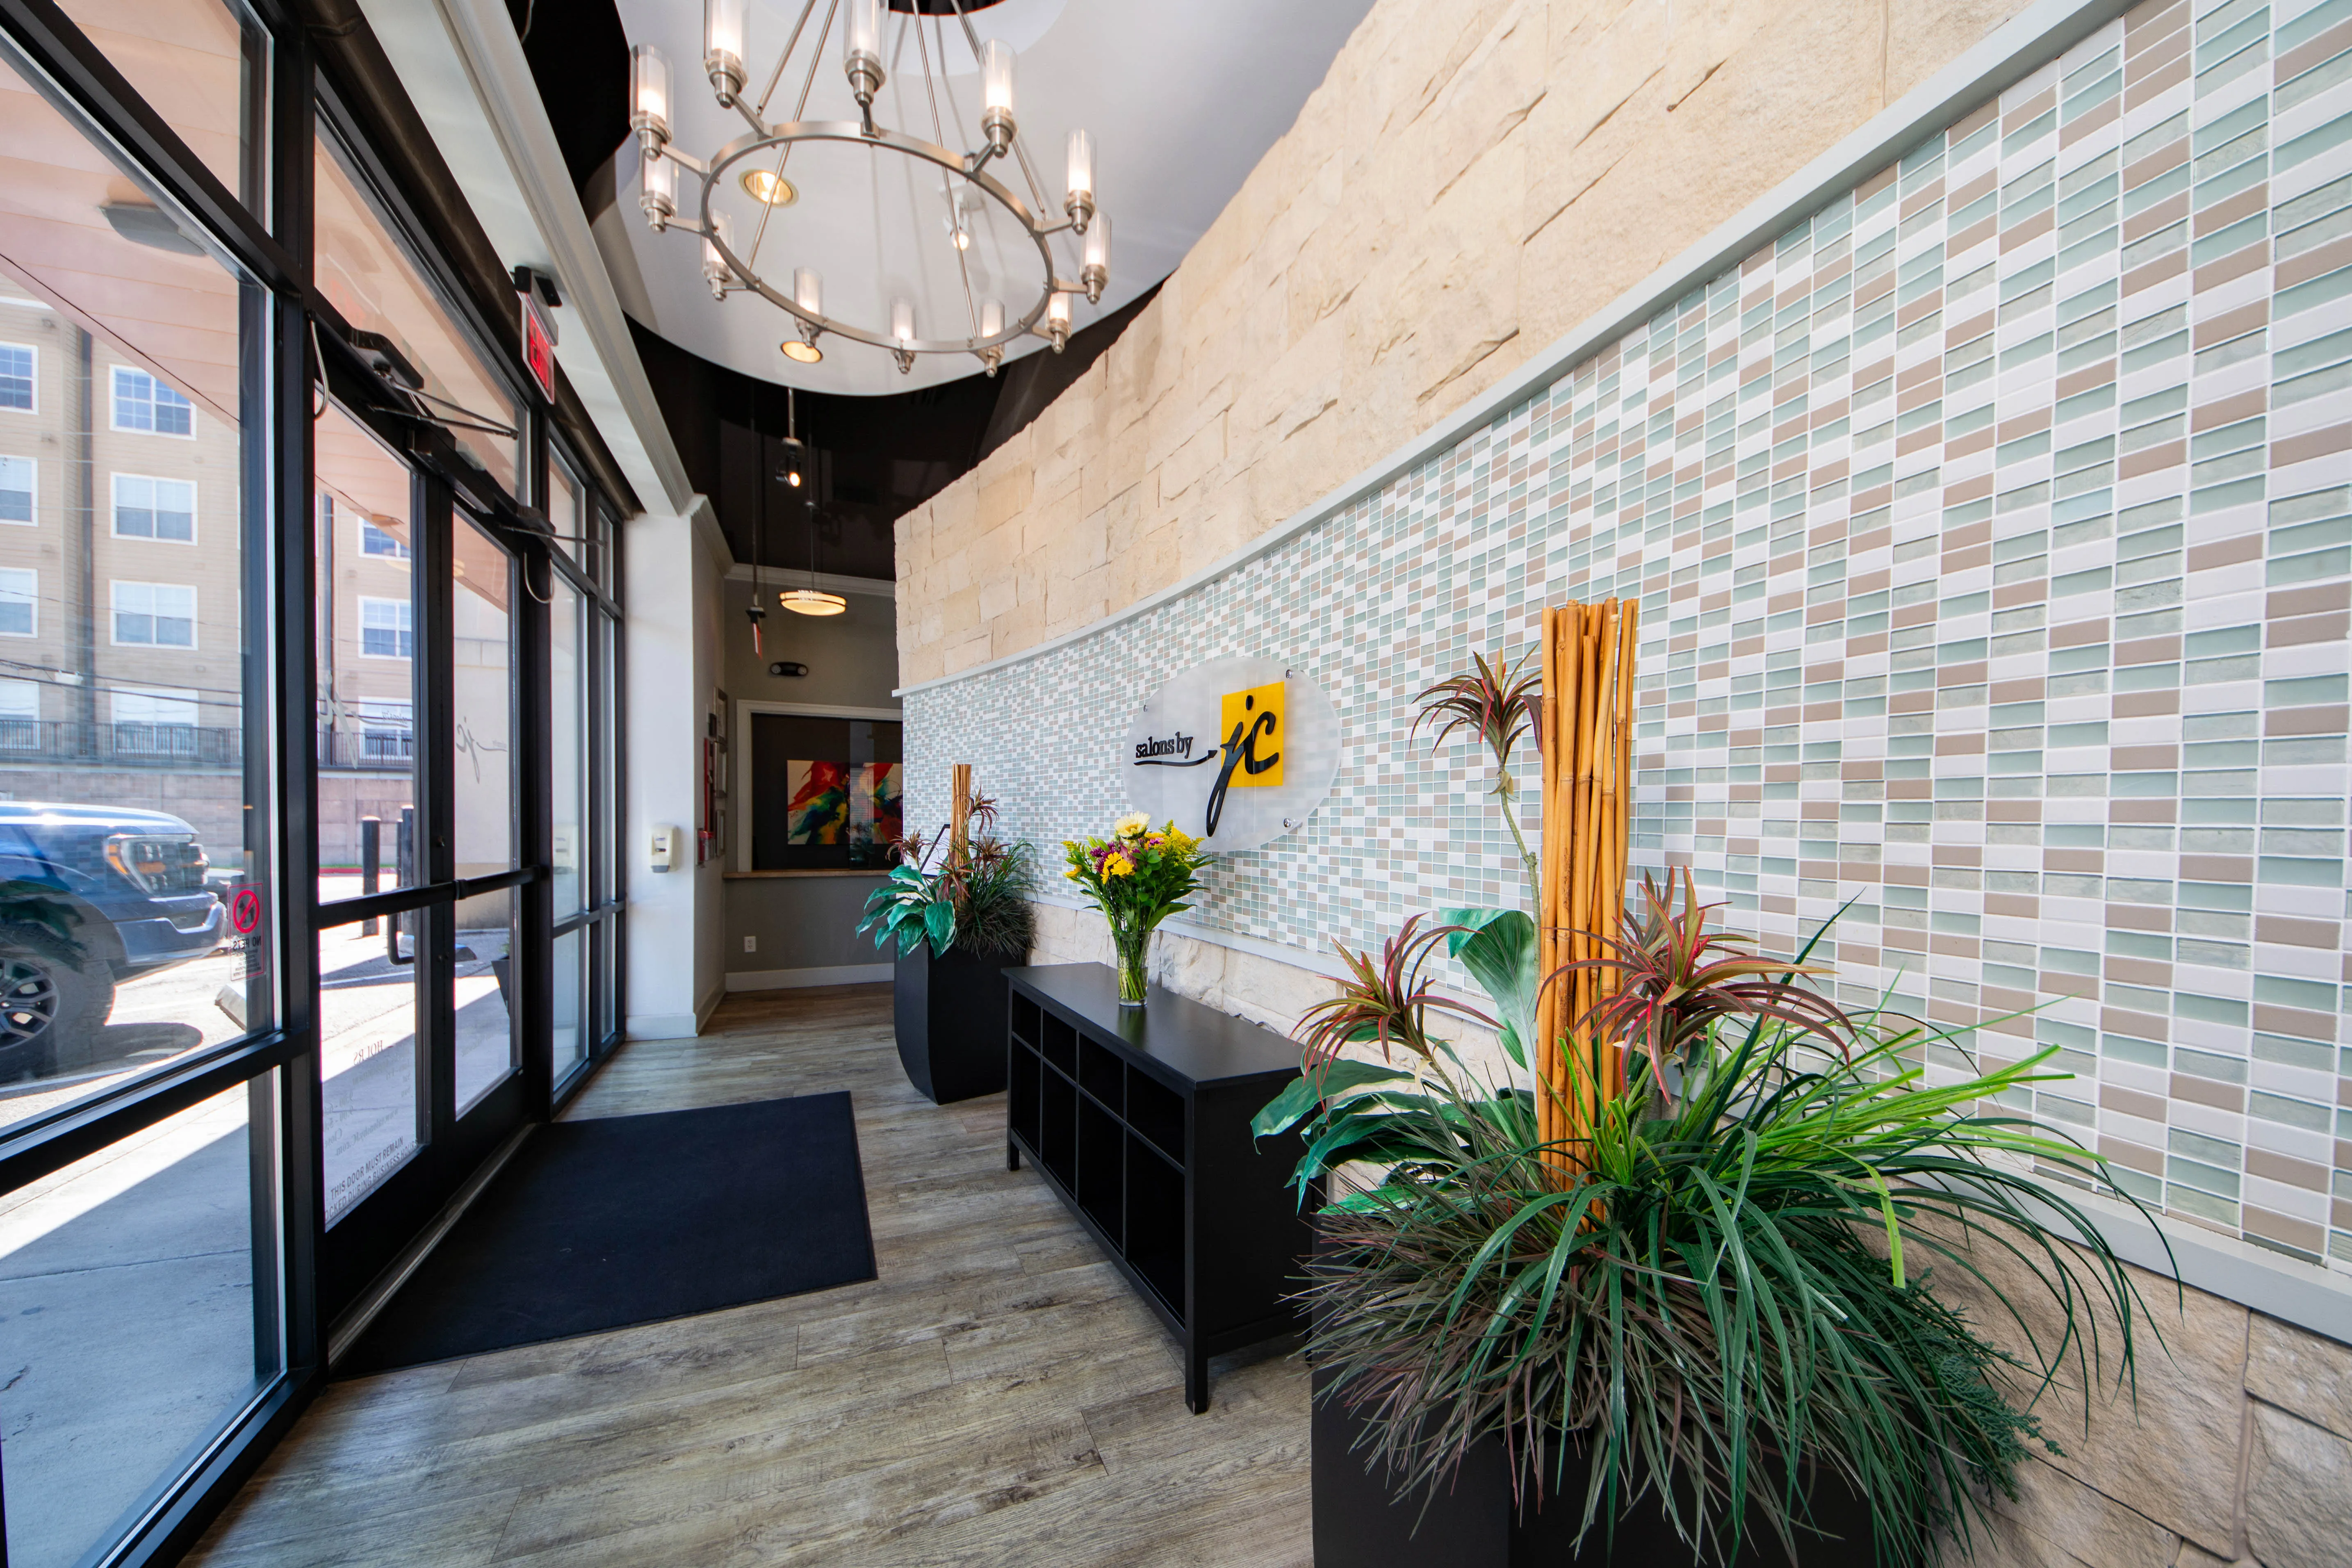
The Concierge Manager model separates daily operations from strategic oversight. A full-time manager handles the location while the owner reviews performance and makes long-term decisions, which fits pre-retirees who do not want to work behind a chair.
Retirement ownership should give you oversight and income potential without recreating the demands of a full-time job. The Salons by JC model is designed for semi-absentee ownership, with a full-time Concierge Manager supporting daily operations at each location. That structure lets an owner focus on performance, planning, and long-term decisions rather than managing every appointment, tenant question, or staffing issue.
Own the business, not the job
A salon suite franchise is not built around the owner working behind a chair. The Concierge Manager serves as the on-site operational leader, helping coordinate the location and maintain the experience for independent beauty and wellness professionals. The owner can review key metrics, evaluate operational priorities, and work with the support team on strategic decisions while remaining removed from routine floor-level responsibilities.
This distinction matters for someone who does not want to work full time in retirement. It also creates a clearer role for an owner who wants to stay engaged on a schedule that fits personal goals. Semi-absentee does not mean completely effort-free. It means the business has an operating structure that separates ownership responsibilities from daily execution. Learn more about semi-absentee franchise ownership and how investors can evaluate the time commitment before moving forward.
No salon or beauty-industry background is required. Salons by JC provides training and support, while the Concierge Manager model supplies day-to-day leadership at the location. That combination can make the opportunity more practical for a professional transitioning from a career in another industry or entering business ownership later in life.
The model also supports a deliberate retirement plan because it gives the owner a defined management lane. You can establish reporting expectations, set review rhythms, and make decisions based on business performance instead of being the person responsible for every service delivered. Read more about the Concierge Manager model before comparing this structure with other investment options.
Funding is a separate planning question. If retirement assets may be part of the capital strategy, review the guide on how to use a 401(k) to buy a franchise. Do not assume every approach has the same requirements or risks.
Talk to a franchise consultant about building a sellable retirement asset.
Building a Retirement Asset You Can Sell: Franchise Resale Value
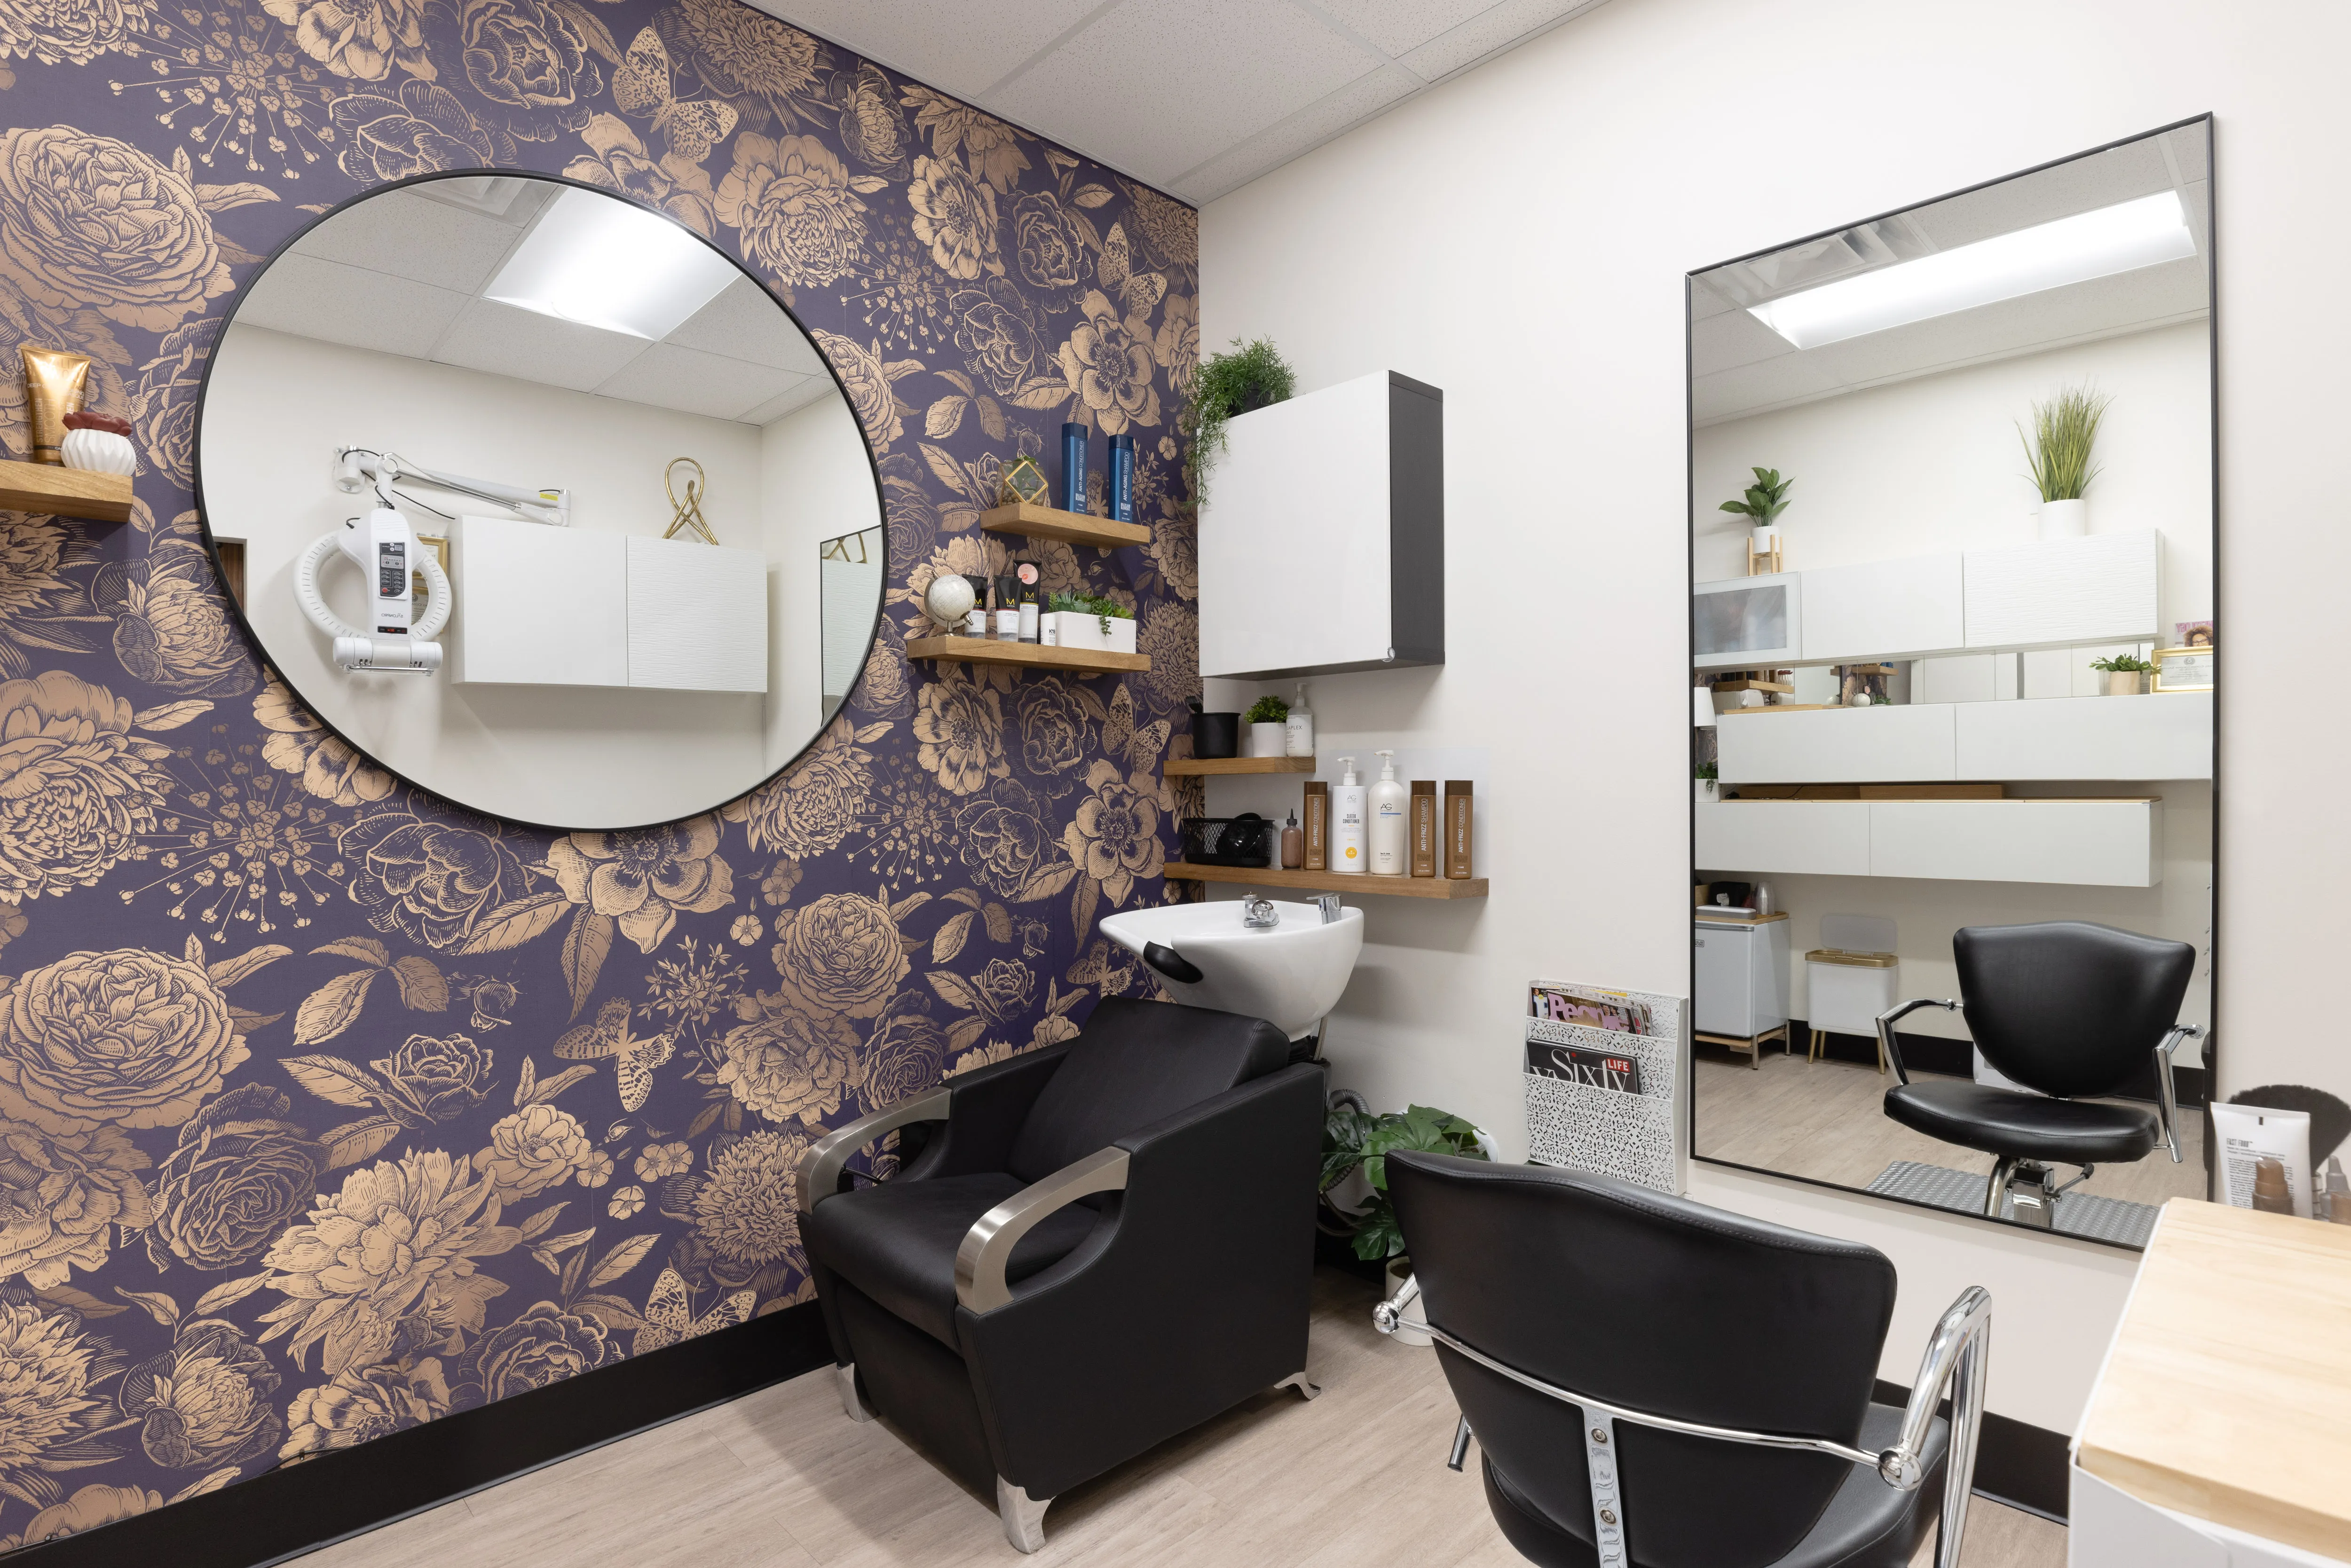
Franchise resale value comes from a documented lease portfolio, renewal history, operating performance, and management systems. A profitable salon suite location can become a sellable asset that supports a later exit or structured retirement transition.
Retirement spending is designed to be used. A profitable franchise can be different: it may continue producing income while you own it, then become a business asset you can sell. That distinction matters when building a retirement plan because the goal is not only to fund today’s lifestyle. It is also to preserve options for tomorrow, including a potential sale, a transfer to family, or a structured exit.
For Salons by JC, the underlying model is tied to recurring commercial activity. Franchisees lease private salon suites to independent beauty and wellness professionals, creating a tenant-based business rather than relying on one operator’s billable hours. Weekly suite rentals and convenience fees provide multiple revenue streams, while the reported 92% lease renewal rate can make the location more attractive to a prospective buyer. A consistent tenant base may reduce vacancy risk and provide clearer operating visibility during due diligence.
Resale value is never automatic. Buyers typically examine financial statements, lease terms, local demand, suite occupancy, operating systems, staff structure, and the condition of the location. A franchise owner who maintains clean records, follows the operating model, supports tenant retention, and plans for a transition is better positioned to demonstrate the business’s quality. The franchise exit strategy should be considered well before a sale is necessary, not after an owner has already decided to leave.
Funding also belongs in the wider ownership discussion. Some investors explore ROBS as a way to use qualified retirement funds to buy a business, subject to compliance requirements and professional guidance. The IRS describes ROBS as an arrangement that can use retirement funds to finance a new business or franchise. Investors considering this route can review how to use a 401(k) to buy a franchise before speaking with qualified advisors.
Estate planning with a franchise asset
A franchise can create responsibilities that extend beyond the owner’s retirement date. Estate planning should address who receives the ownership interest and who can manage the business during a transition. Owners should also decide whether a sale is more appropriate than a transfer. These decisions become especially important when family members have different skills, interests, or financial needs.
Business owners should integrate the franchise into their broader legacy and financial plan rather than treating it as a separate asset. Comprehensive estate planning can help protect the owner’s financial future and clarify the intended path for the business. It may also reduce confusion for heirs if the owner becomes incapacitated or dies unexpectedly. Estate planning is identified as a core consideration for franchise owners in guidance from Aprio. Review ownership, insurance, tax, and succession questions with qualified legal and financial professionals.
Frequently Asked Questions
What is a retirement planning franchise?
A retirement planning franchise is a business investment evaluated as part of a broader retirement strategy. Instead of relying only on portfolio withdrawals, the owner may build an operating asset that produces income and could have resale value. A salon suite franchise uses leased commercial space, private suites, and recurring rentals to create a real estate-based business model. It remains a business investment, not a guaranteed retirement-income product.
How does franchise ownership contribute to retirement planning?
Ownership can add a potential income stream before and during retirement while giving you more control over an operating asset than a passive investment alone. Planning should include available capital, debt service, taxes, manager compensation, reinvestment, and a future exit strategy. Income solely from owning an income-producing business may sometimes be excluded from the Social Security earnings test when no post-retirement services are performed. But eligibility depends on the facts and applicable rules. See the Social Security guidance and consult a qualified adviser.
Is a salon suite franchise suitable for semi-absentee ownership?
It may be suitable for an investor who wants strategic oversight without performing daily salon services. Salons by JC supports each location with a full-time Concierge Manager, while the franchise model uses weekly suite rentals and convenience fees. The owner still needs to review performance, approve decisions, and maintain adequate operating reserves. Semi-absentee does not mean completely effort-free.
Are there tax advantages to owning a franchise for retirement?
Potential benefits can include ordinary business deductions and, when requirements are met, the qualified business income deduction. The IRS states that eligible pass-through owners may deduct up to 20% of qualified business income under Section 199A. Eligibility, limits, and tax treatment vary, so have a tax professional model the franchise alongside your retirement accounts and other income.
What should I evaluate before investing?
Review these key planning inputs before committing capital:
- Total investment and liquidity requirement
- Financing terms and lease economics
- Renewal history and manager structure
- Training, market demand, and resale assumptions.
Salons by JC lists a total initial investment of approximately $1.3 million to $2.0 million and a 92% lease renewal rate. Treat those figures as planning inputs, not a promise of performance, and complete financial and legal due diligence before committing capital.
Ready to Explore Franchise Ownership?
Retirement planning is stronger when you evaluate income sources, operating responsibilities, and long-term asset value together. A franchise investment conversation can help you determine whether the model fits your financial goals and ownership preferences. To request franchise investment details, contact Salons by JC for investment information. Review the opportunity, consider your available capital, and discuss next steps with your financial and legal advisors.


